What supports the case
- Data Center revenue grew 97% year on year in Q3 2026.
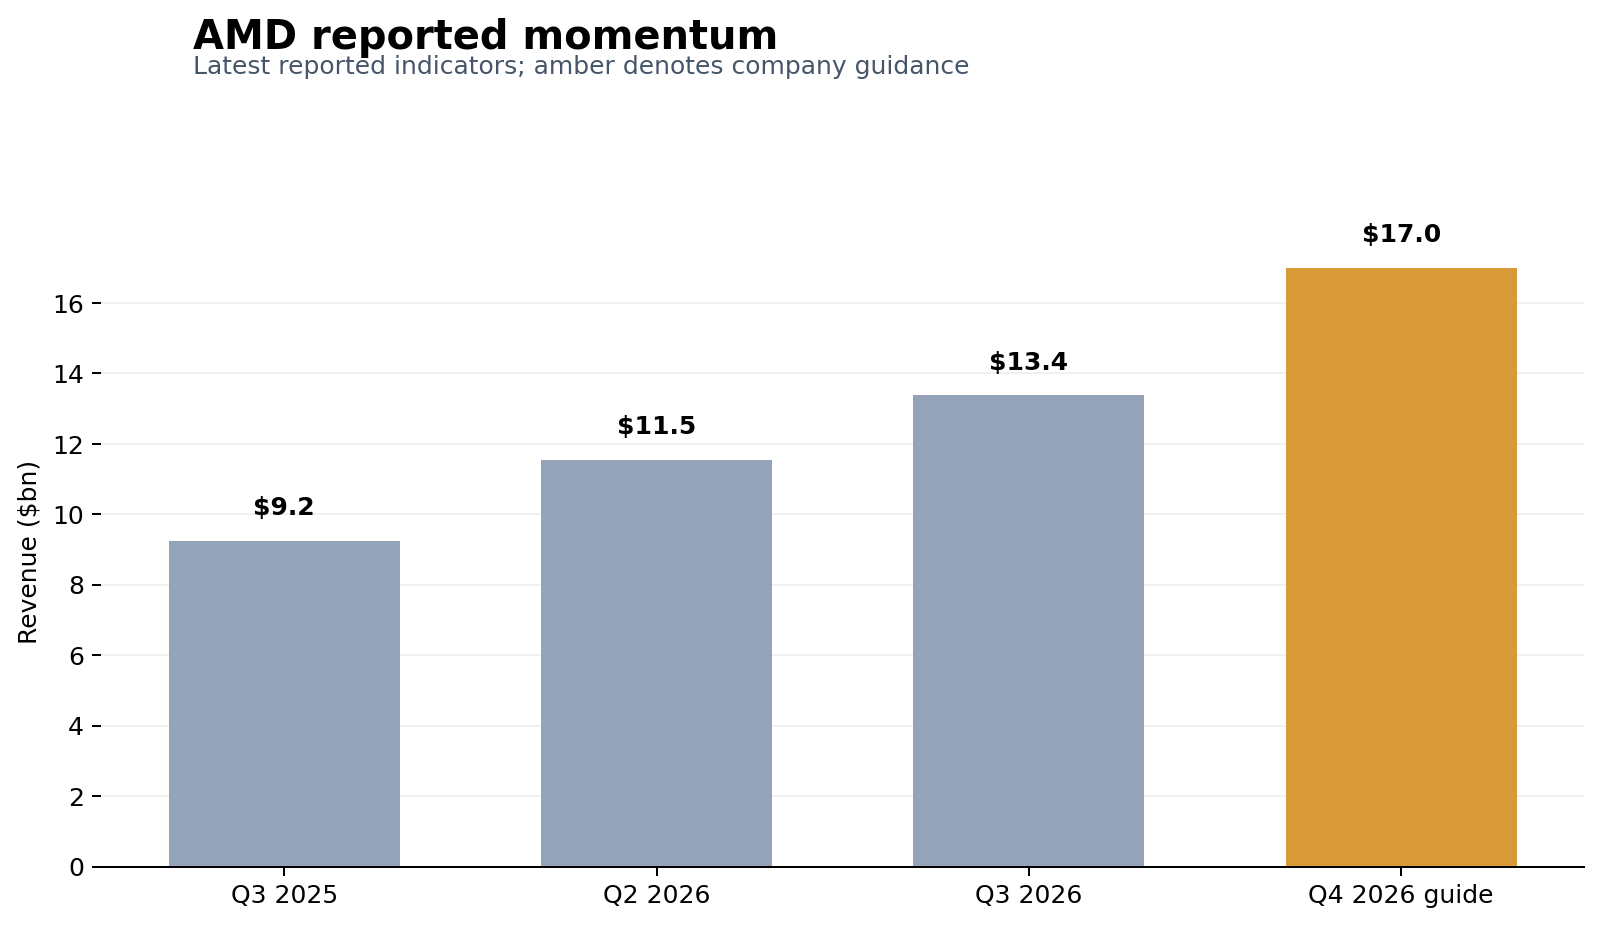
- Q4 guidance points to another material step up in revenue.
- EPYC and Instinct product momentum supports mix improvement.
A compute platform scaling Data Center CPUs and AI accelerators across cloud, enterprise and infrastructure workloads.
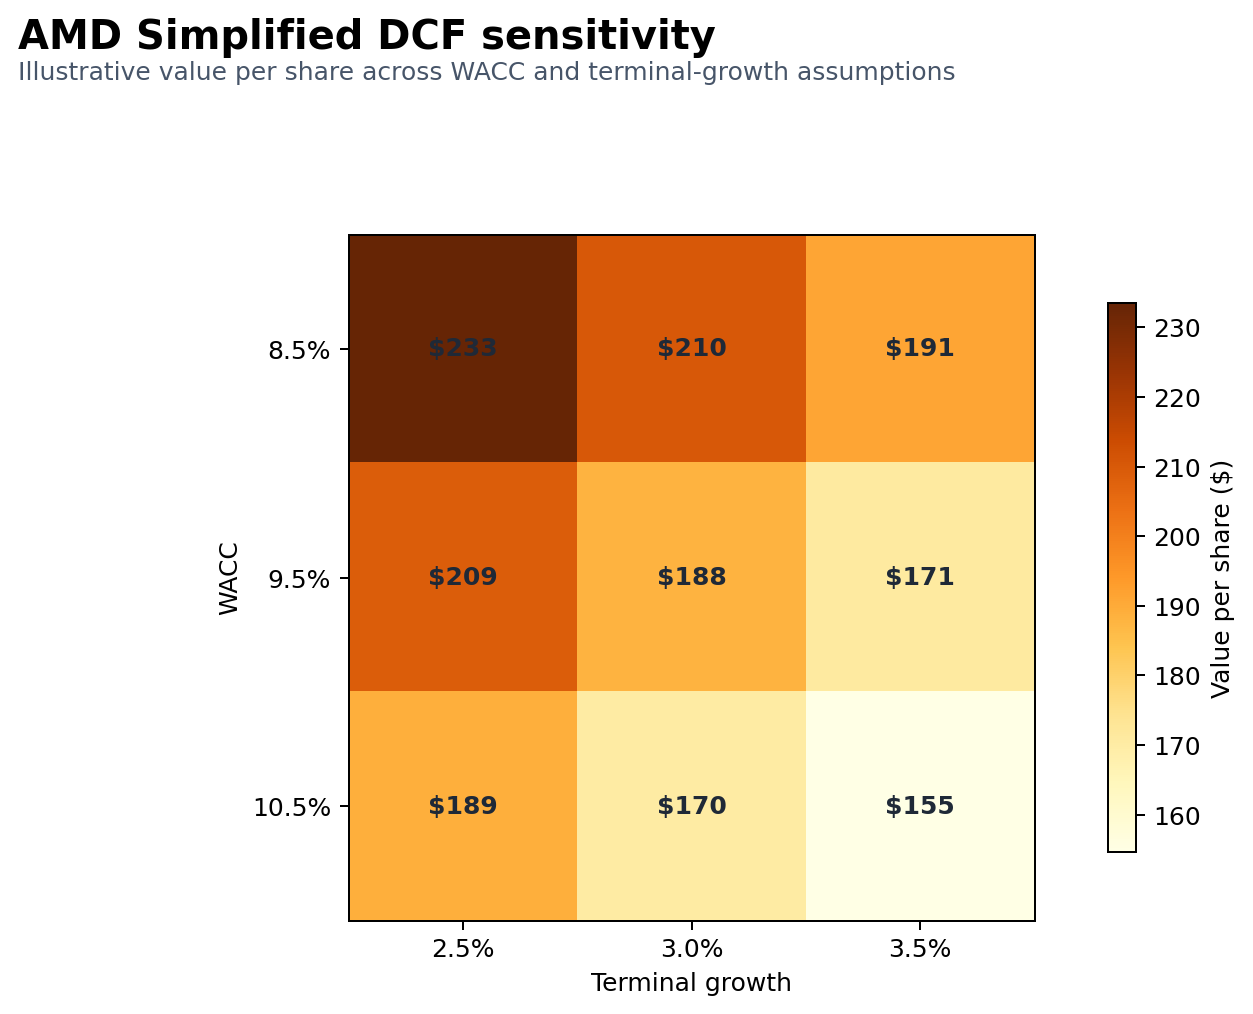
AMD's case depends on sustained execution in Data Center CPUs and GPUs, along with improving software and system-level adoption. The valuation framework tests how much growth and margin expansion are required to justify the current market expectation.
The chart pack separates historical results from the Q4 company-guidance midpoint and makes the model's assumptions visible.
| Metric | Reported evidence | Research read-through |
|---|---|---|
| Revenue | $13.4bn in Q3 2026, up 45% year on year | Record revenue confirms stronger demand across the portfolio. |
| Data Center | $8.5bn, up 97% year on year | AI infrastructure and server compute are increasingly central to the earnings case. |
| Outlook | Q4 revenue of approximately $17bn, plus or minus 3% | Creates a high execution bar and makes the next results release important. |
Download the full research note and the driver-led model. They are educational portfolio materials, not investment advice.
Sources: AMD Q3 2026 earnings release. Figures are current as of 11 November 2026.