What supports the case
- Broad-based contribution across corporate, consumer and asset-management franchises.
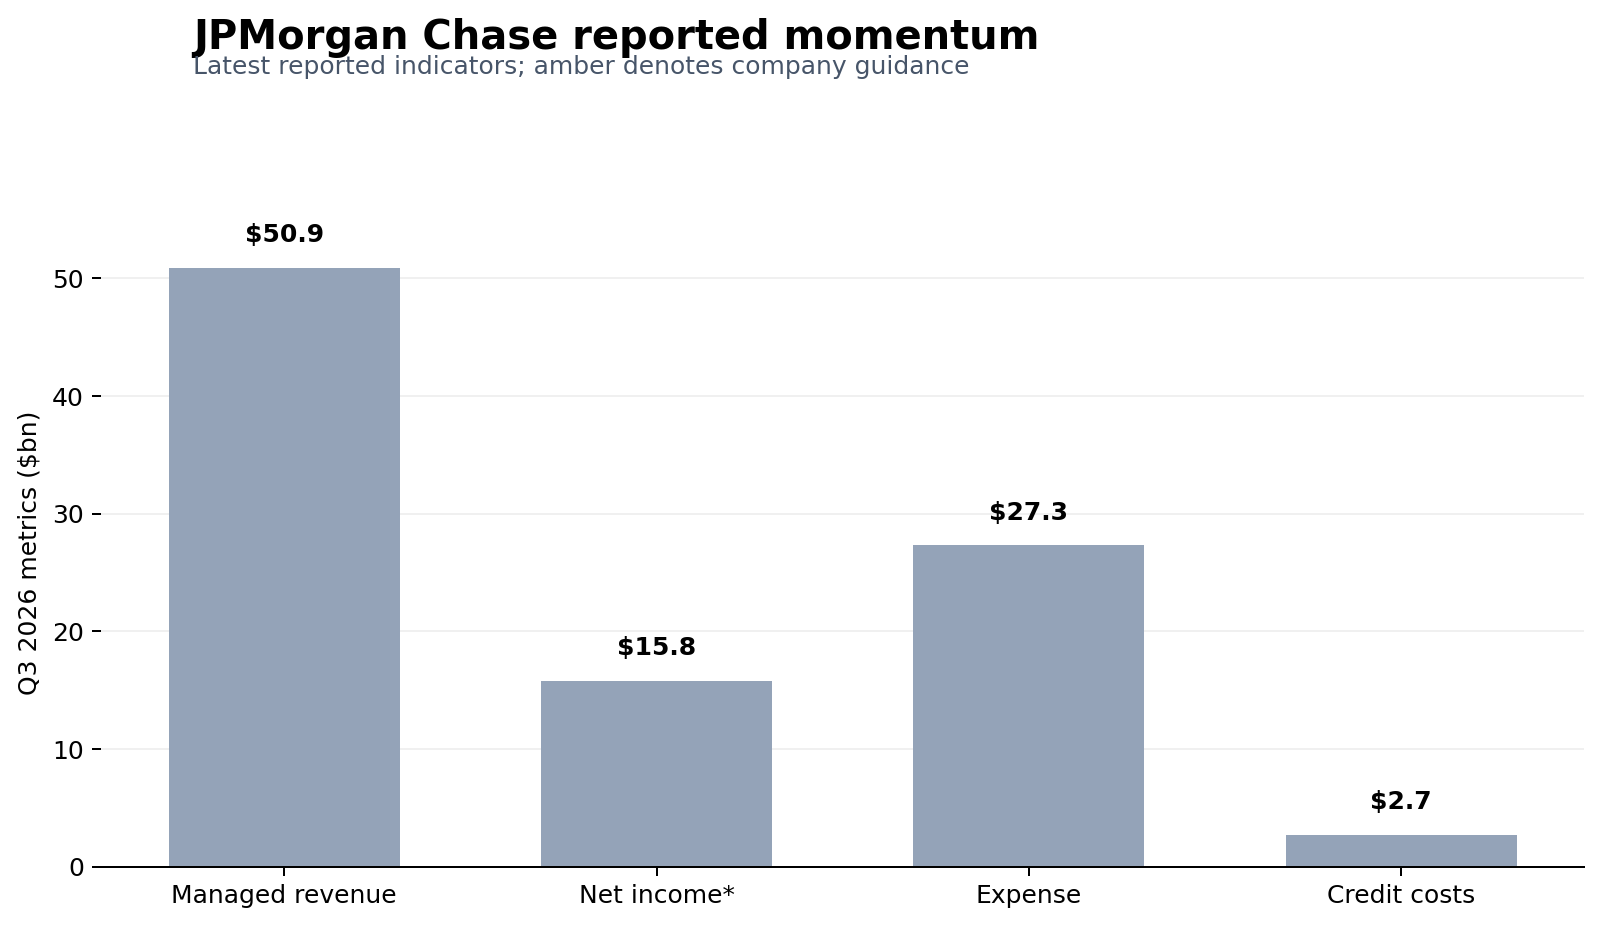
- Managed revenue of $50.9bn and ROTCE of 20% in Q3 2026.
- Capital strength, with standardised CET1 of 13.9%.
A diversified global bank assessed through franchise breadth, credit discipline, capital strength and returns on tangible equity.
JPMorgan is assessed differently from the technology names in the portfolio. The model uses a tangible-book-value framework alongside return-on-tangible-common-equity, credit costs, capital ratios and the earnings mix across consumer, corporate and asset-management businesses.
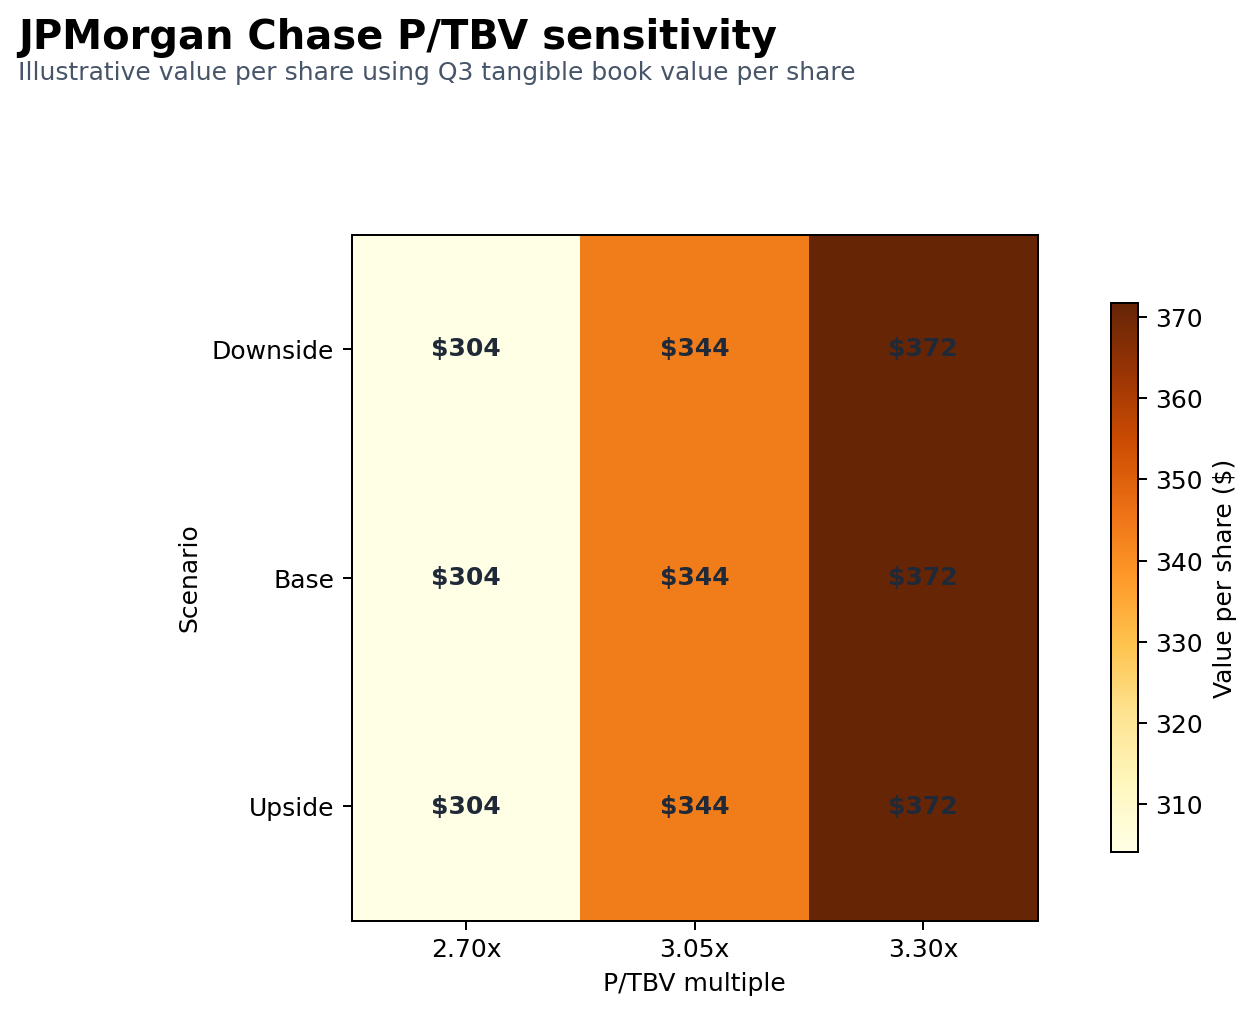
For a bank, the primary valuation cross-check is tangible book value per share and a range of price-to-tangible-book multiples, not a standard industrial-company DCF.
| Metric | Reported evidence | Research read-through |
|---|---|---|
| Revenue | $50.9bn managed revenue | Shows broad franchise income across business lines. |
| Credit costs | $2.7bn, including $2.2bn of net charge-offs | Credit quality and reserve trends remain the central cycle indicators. |
| Capital | Standardised CET1 of 13.9% | Provides a buffer and supports distributions, subject to regulation and earnings. |
Download the full research note and the driver-led model. They are educational portfolio materials, not investment advice.
Sources: JPMorgan Chase Q3 2026 earnings release. Figures are current as of 11 November 2026.