MRNA · NASDAQ · HEALTHCARE

Moderna

A commercial-stage mRNA company moving from a COVID-led revenue base towards a broader respiratory and oncology pipeline.

$1.3bnQ3 2026 revenue
29.0%Revenue growth
$162mQ3 GAAP net income
$8.0bnCash and investments
Investment view

Broader products and a pipeline must convert into repeatable earnings.

The research case centres on Moderna's transition beyond a single-product COVID franchise. Improved profitability and a higher 2026 outlook are constructive, but the value of the long-term case still depends on commercial launches, pipeline delivery and continued cost discipline.

What supports the case

  • Q3 revenue grew 29% year on year to $1.3bn and the company returned to GAAP profitability.
  • Management raised its 2026 revenue-growth outlook to 15% to 25%.
  • Cash and investments of $8.0bn provide funding flexibility for commercial and development activity.

Risks to monitor

  • Seasonal vaccine demand and uncertainty around the size of the COVID market.
  • Clinical, regulatory and commercial execution across the pipeline.
  • Long-dated valuation assumptions, cost control and future cash use.
Python analysis

Reported momentum and valuation sensitivity.

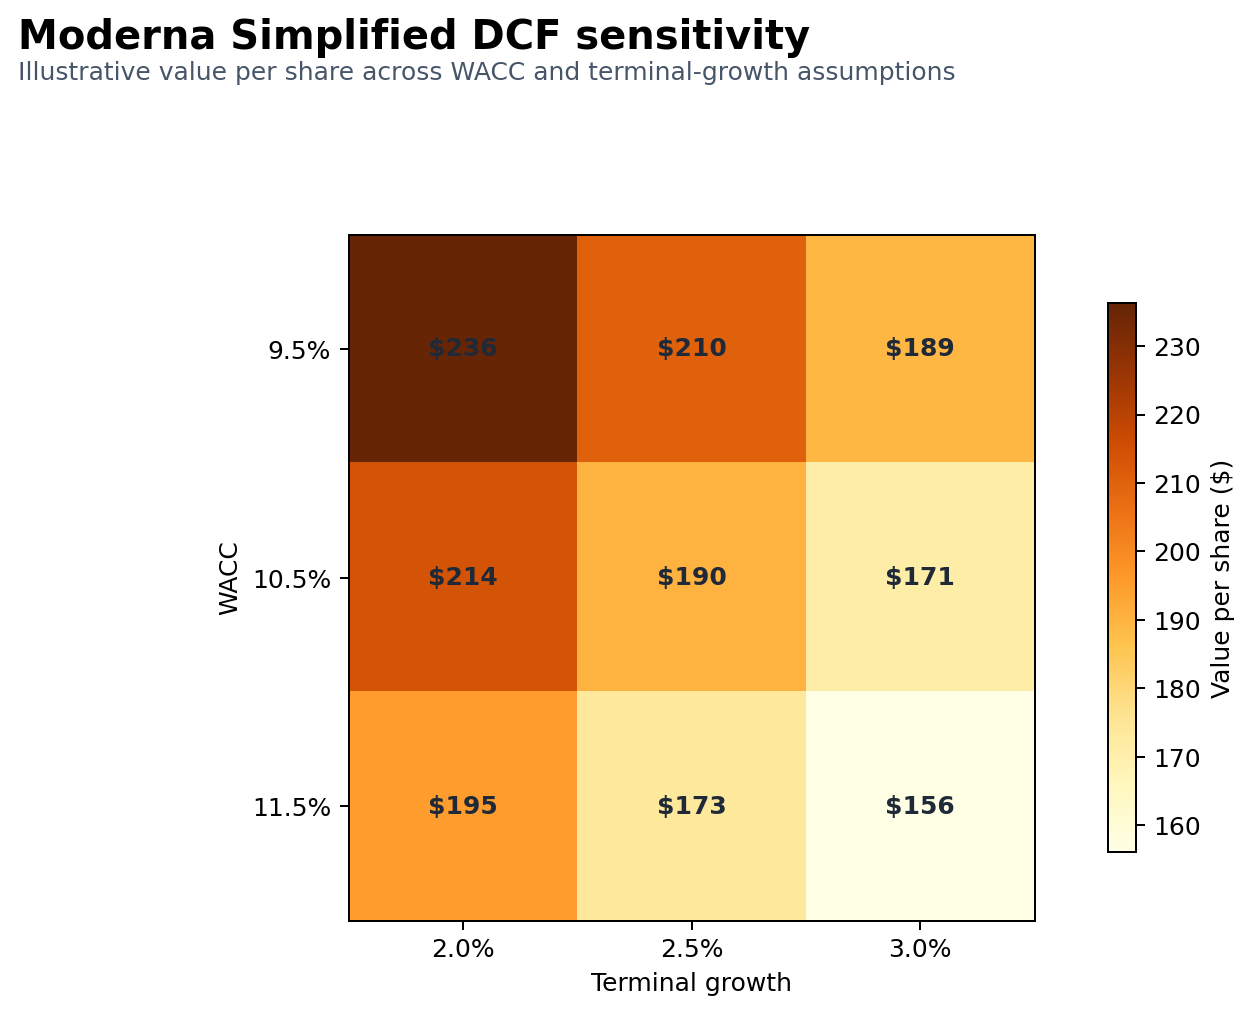
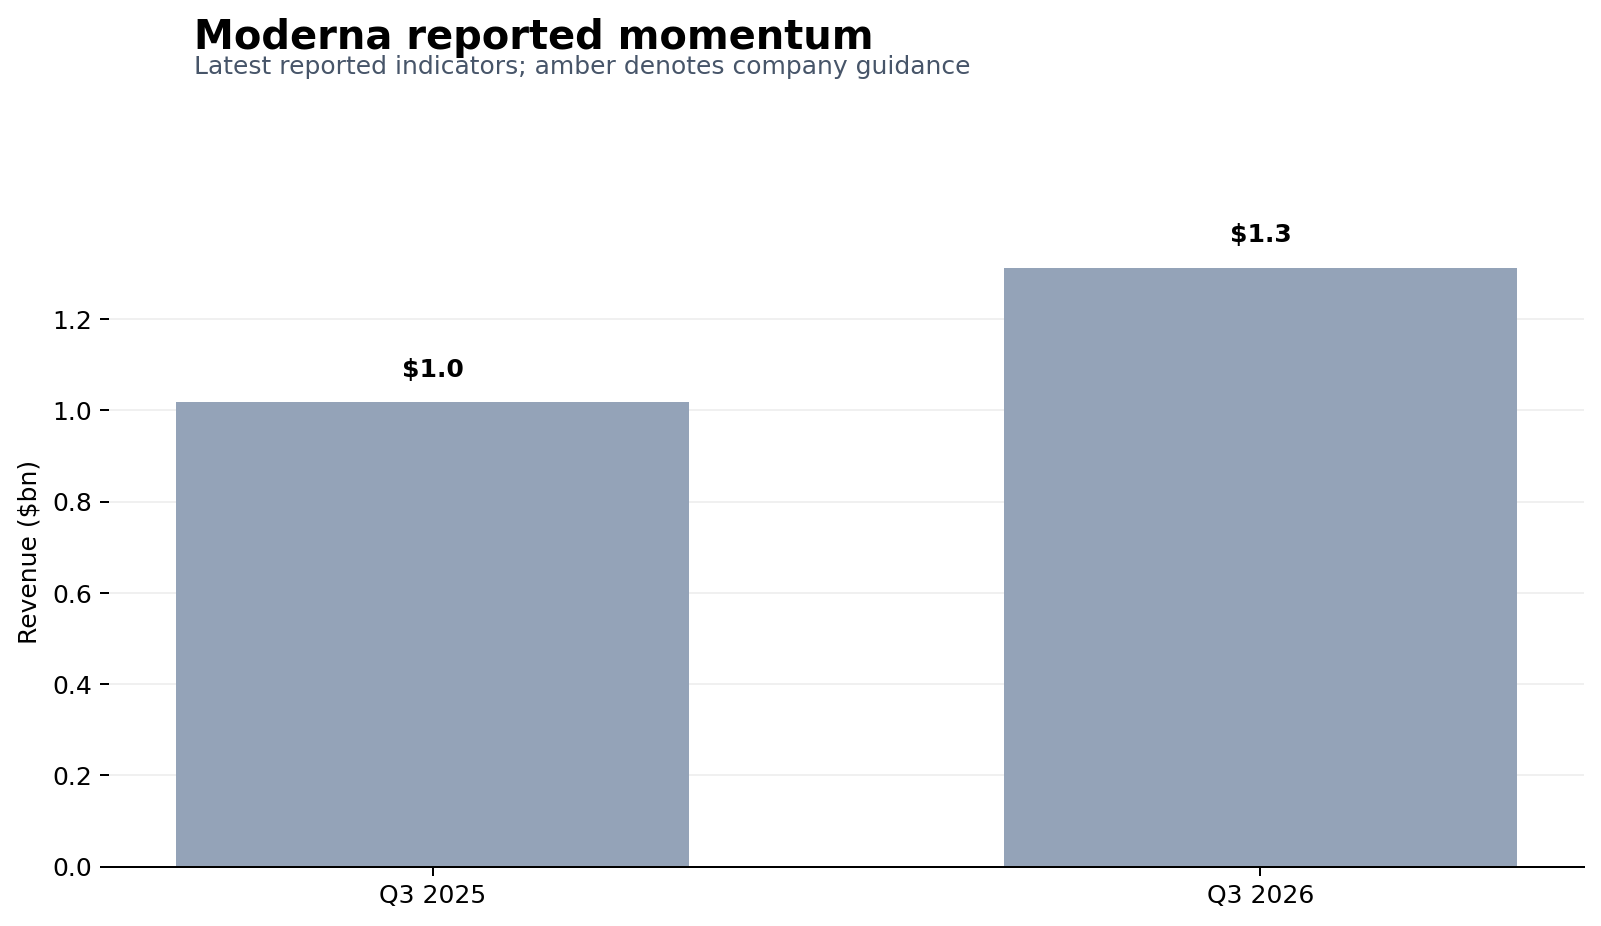
The chart pack shows the most recent year-on-year revenue change and an illustrative DCF sensitivity across discount-rate and terminal-growth assumptions.

Moderna reported revenue momentum
Q3 2025 and Q3 2026 reported revenue.
Moderna DCF sensitivity
Illustrative DCF sensitivity across discount-rate and terminal-growth assumptions.
Financial review

What the latest release says

MetricReported evidenceResearch read-through
Revenue$1.3bn in Q3 2026, up 29% year on yearInternational COVID vaccine sales and strategic partnerships supported growth.
Profitability$162m GAAP net income, versus a $200m loss in Q3 2025Cost control and sales conversion improved the quarter, but seasonality remains relevant.
Outlook and cash2026 revenue-growth outlook of 15% to 25%; expected year-end cash and investments of $8.1bn to $8.3bnLiquidity supports the pipeline, while future product diversification remains the key value driver.
Supporting work

Inspect the work behind the case.

Download the full research note and driver-led model. They are educational portfolio materials, not investment advice.

Sources: Moderna Q3 2026 earnings release. Figures are current as of 11 November 2026.