Investment view
Exceptional execution, with expectations already high.
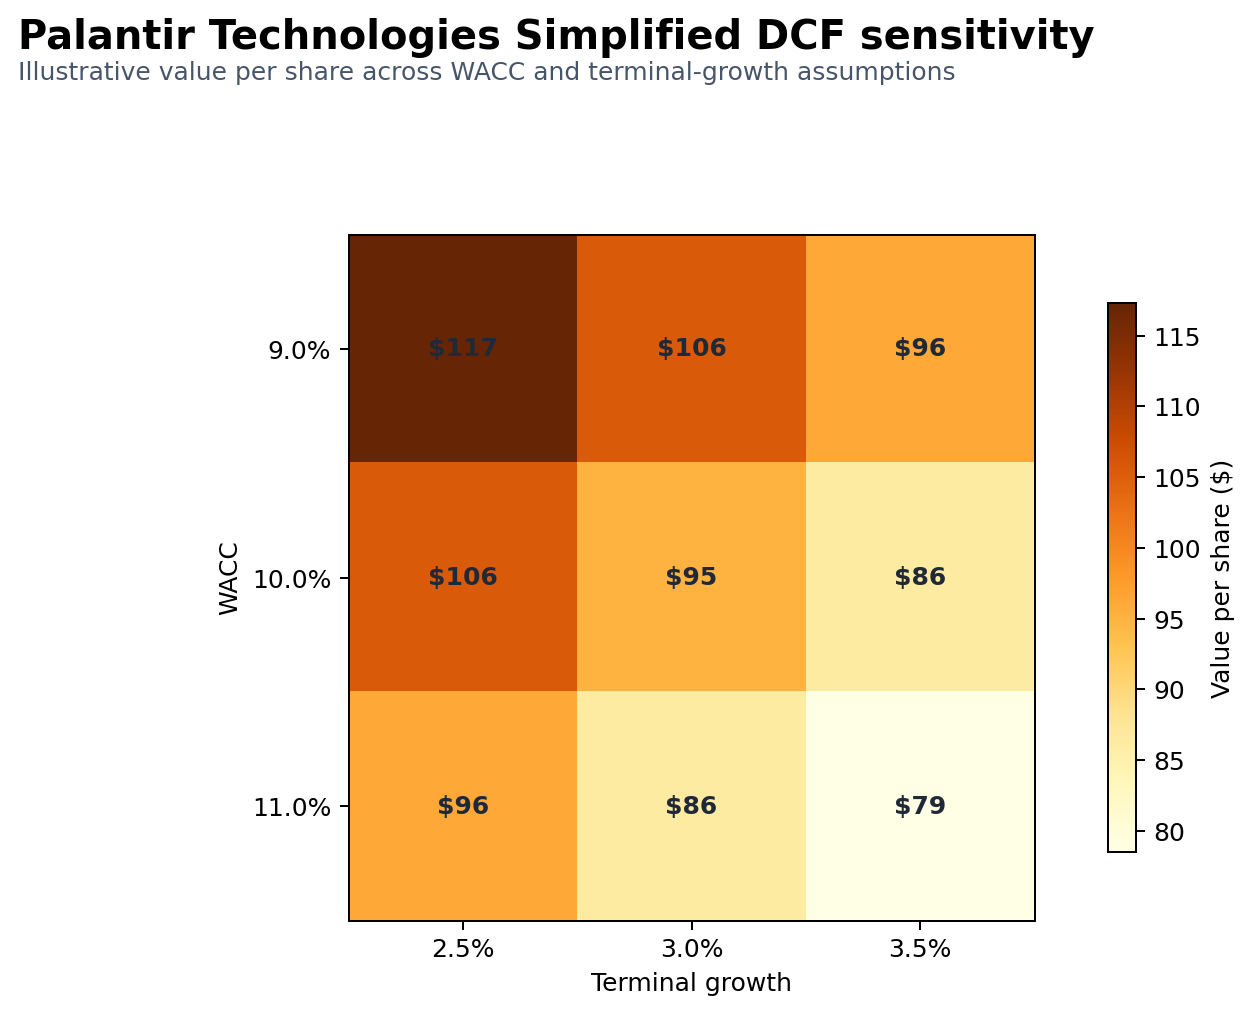
Palantir combines fast revenue growth with very high operating leverage, particularly in US commercial. The central trade-off is whether that execution can persist long enough to justify the substantial valuation premium already reflected in the share price.
What supports the case
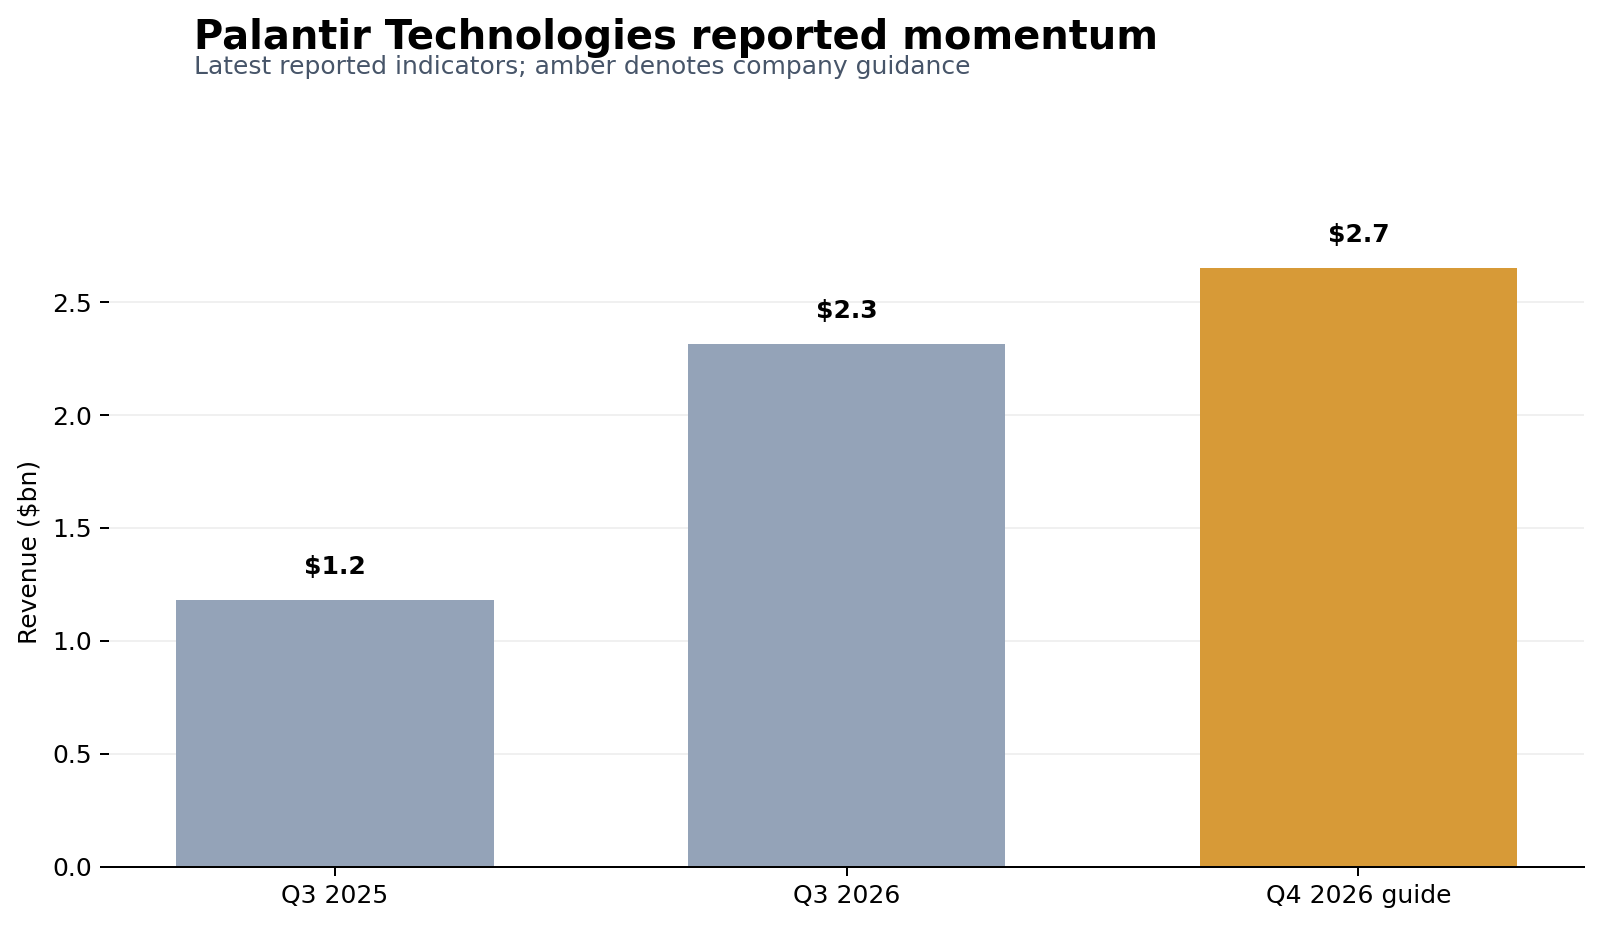
- Q3 revenue grew 96% year on year, while US commercial revenue grew 148%.
- Q3 GAAP operating income was $1.08bn, with a 47% operating margin.
- FY26 guidance was raised to $8.530bn to $8.534bn of revenue and $4.8bn to $5.0bn of adjusted free cash flow.
Risks to monitor
- High valuation expectations and multiple-compression risk.
- Large-deal timing, customer concentration and government procurement cycles.
- Execution risk as growth expands across a broader commercial customer base.